Portfolio Intelligence · For Banks & Credit Unions
See your borrowers clearly, and help them grow.
Portfolio Intelligence is a partnership between your bank, your borrowers, and GLI. Every borrower who opts in gets a clear view of their own business, and your team gets live cash flow, key lending ratios, and a Health Score for each one. Built on the same platform our members use to run and grow their businesses.
Portfolio Intelligence is separate from Green Leaf membership. A bank can invite its existing borrowers, or new and existing borrowers in a particular book of business, to join through the bank’s partnership with GLI. Nothing is shared until the owner signs a written consent, and a lender never sees anything the owner can’t see in their own view.
The problem
Annual statements tell you where a borrower was. Not where they are.
Most commercial lending relationships run on an annual package, often months after fiscal year-end. In between, the bank and the borrower are working from old numbers. Questions wait for the next review, and good chances to grow together get missed.
When both sides see the same current numbers, the relationship changes. Conversations happen earlier, decisions move faster, and the owner gets a lender who actually knows the business.
12×more visibility.
Monthly statements instead of an annual package.
One score.
A live Health Score the bank and the owner both see.
Whole portfolio.
Every participating borrower on one comparable dashboard.
What it is
One shared view of the business, for the owner and the bank.
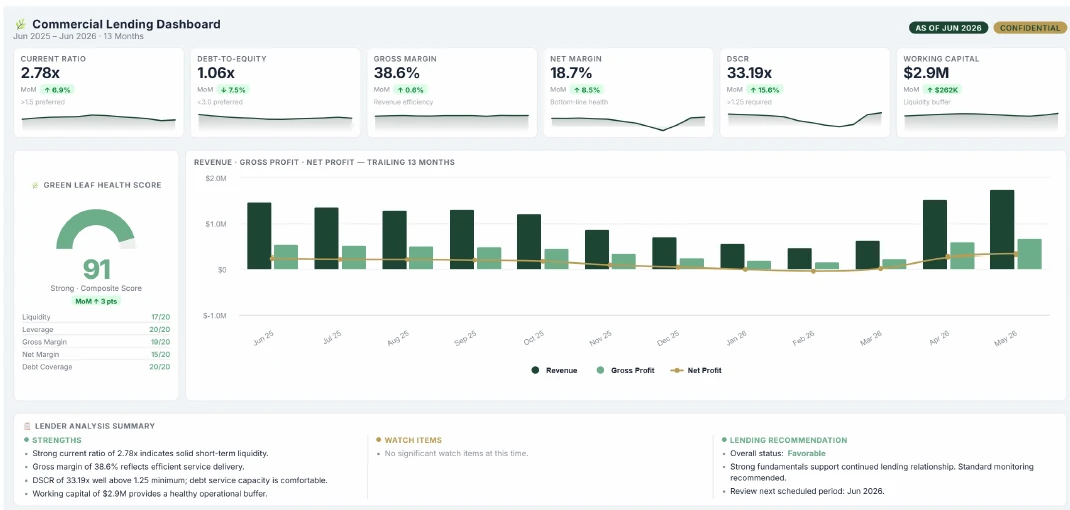
Green Leaf Intelligence sits above a borrower’s financial systems and unifies their data into a single source of truth: live cash flow and financial metrics, clean monthly statements, a proprietary live Health Score, and an anonymized benchmark that deepens as the network grows.
When a bank or credit union partners with GLI, it invites borrowers to join. Borrowers who agree get a banking-focused view of their own business, paid for by the bank. The lender gets the Lending Dashboard for every borrower who opted in. Both sides see the same numbers.
The result is a partnership built on current information: faster reviews, earlier conversations, and a bank that is ready when the business needs to grow.
Capabilities
What the Lending Dashboard gives your team.
01
Live Financial Visibility
Income statement and balance sheet metrics for every participating borrower, live from their connected systems, with clean statements after each month-end close. No more waiting on the annual package or chasing interim statements.
02
Lending-Ratio Monitoring
The ratios your credit team already lives by, calculated automatically and kept current: debt service coverage, current ratio, quick ratio, debt-to-equity, net-debt-to-EBITDA, interest coverage, and months of cash on hand. Trendlines show direction, not just a single point in time.
03
Cash-Flow Tracking
Live visibility into operating cash flow, free cash flow, receivables aging, and seasonal swings, so repayment capacity is clear as it develops.
04
Live Health Score
Every participating borrower carries a live Green Leaf Health Score spanning growth, profitability, cash flow, working capital, and leverage. The owner sees the same score, so a dip becomes an early conversation between partners, not a surprise at review time.
05
Growth Opportunities
When a borrower is growing, adding equipment, or taking on new financing, the dashboard points to it as a chance for the bank and the owner to talk about what the business needs next. The owner sees the same view in their own dashboard.
06
Portfolio-Comparison Dashboard
Every enrolled borrower on one screen: sortable by Health Score, exposure, ratio trends, and open notes, with anonymized peer context that deepens as the network grows.
The dashboard
One screen. Your whole book.
The Lending Dashboard puts every enrolled borrower side by side: current Health Score, movement since last month, the ratios that matter, and anything worth a conversation. Click into any borrower for full monthly statements and trend history.
Sample portfolio · illustrative data
Borrower
Health Score
Change (Mo)
DSCR
Net Debt / EBITDA
Months of Cash
Note
Cedar Ridge Landscapes
84
+2
1.9x
1.4x
3.8
None
Summit Mechanical
77
0
1.6x
2.1x
2.9
None
Lakeside Pool Co.
71
-4
1.3x
2.8x
1.7
Score dip
Ironwood Contracting
68
-1
1.2x
3.0x
1.4
Equipment financing opportunity
Prairie Property Care
88
+3
2.2x
0.9x
4.6
Growth signal
Sample portfolio, illustrative data. Borrower-level drill-down includes full monthly statements, ratio trendlines, cash-flow history, and peer benchmarking.
Borrower detail view · sample data
For the borrower
A partnership your borrowers will value.
This is not monitoring software bolted onto a loan file. Borrowers who join get a banking-focused view of their own business, with the same statements, ratios, cash flow, and Health Score their lender sees, and can upgrade to full Green Leaf membership for the complete picture.
An owner who watches their own numbers runs a stronger business, and a stronger business is a stronger credit. The bank pays for the program, the owner gets a tool that helps them grow, and both sides work from the same facts. It is a relationship story first.
Every enrolled borrower receives
Monthly financial statements, unified in one place
The live Green Leaf Health Score and its trend
The key lending ratios, tracked over time
Cash-flow tracking and receivables visibility
Anonymized peer context that deepens as the network grows
Upgrading to full membership adds
Monthly business value, expressed as a share price
The Strategic Blueprint: a prioritized roadmap for growing value
The full Green Leaf Command Center
Quarterly market updates and the member resource center
How it works
Four steps, and your team does almost none of them.
01
Invite
Invite existing borrowers, or new and existing borrowers in a particular book of business. Borrowers who want in sign a standard consent authorizing GLI to share their dashboard with you. The bank sponsors the membership.
02
Connect
GLI's team onboards each borrower and connects their accounting and related financial systems through a read-only integration. Financial systems only; no operational, HR, or sales systems are touched. The borrower does the approving; your team does nothing technical.
03
Stay current
Cash flow, ratios, and Health Scores stay current on your Lending Dashboard, with clean statements after each month-end close. The dashboard highlights score changes, ratio movement, new financing needs, and growth.
04
Grow together
Relationship managers walk into every conversation current. Reviews move faster, small issues get talked through early, and the bank is first in line when the business needs to grow.
The model
A simple model that pays for itself.
The institution sponsors a banking-focused membership for its enrolled borrowers and receives the Lending Dashboard across the portfolio. Pricing is per enrolled borrower per month, with institutional tiers by portfolio size. One equipment loan kept in-house can cover a year of the program.
Institutions can enroll a handful of key relationships or an entire segment of the commercial book. Borrowers who want the full picture can upgrade to complete Green Leaf membership on their own.
Built for consent, confidentiality, and compliance.
Borrower consent, always.
Nothing is shared with a lender without the borrower's written authorization. Borrowers know exactly what their lender sees, and the borrower view and lender view are drawn from the same underlying data. A lender never sees anything the owner can’t see in their own view.
Read-only by design.
GLI connects to borrower financial systems through a read-only integration. We cannot move money, change records, or transact in any connected system, and no operational, HR, or sales systems are connected in this program.
Confidential and segregated.
Each institution sees only its own enrolled borrowers. Any benchmarking shown to lenders and members is anonymized. No borrower's identity or financials are ever exposed to other members or other institutions.
Independent by design.
Green Leaf Intelligence is not a lender, a broker, or a deal advisor. We earn no commissions and have no position in any credit decision. Our only role is accurate, current intelligence.
Questions
Frequently asked questions.
Does the borrower know the lender can see their dashboard?
Yes. Sharing requires the borrower's written consent at enrollment, and the borrower can see exactly which views are shared. Transparency is a condition of the program.
What does the lender actually see?
Monthly financial statements, live lending ratios and cash flow, the live Health Score and its movement, and anonymized peer context. Lenders never see a borrower’s Enterprise Value, share price, Index position, Blueprint, or forecast.
How current is the data?
Cash flow, ratios, financial metrics, and the Health Score are live from the borrower’s connected systems. Full financial statements are finalized after each month-end close.
What systems does GLI connect to?
For this program, financial systems only. GLI connects to QuickBooks Online, QuickBooks Desktop, Xero, and FreshBooks, and can also work from a manual trial balance provided by the borrower each month. No operational, HR, or sales systems are connected. GLI's onboarding team handles the connection with the borrower directly.
What if a borrower's books are messy?
Data-integrity checks are part of the platform. GLI flags variances, inconsistencies, and gaps, and works with the borrower to resolve them, which by itself often improves the quality of what the lender receives.
Can we offer this at origination or renewal?
Yes. Some institutions invite a particular book of business at origination or renewal, much like a monthly reporting covenant, except GLI does the work instead of the borrower’s bookkeeper. It works best as a partnership: the borrower signs the consent and sees everything that is shared.
Is GLI a substitute for our own credit analysis?
No. Portfolio Intelligence is an information layer. Credit decisions, covenant enforcement, and risk ratings remain entirely with the institution.
Which industries are covered today?
GLI currently serves service-based businesses in the roughly $3M to $30M revenue range across outdoor property services, mechanical and structural trades, and property construction and improvement, with additional cohorts launching.
Partner with your borrowers on current numbers.
See the Lending Dashboard with your own portfolio in mind. A demo takes thirty minutes.